Printing Imagination (and Homes!)

Sabeena Bubber • February 11, 2016


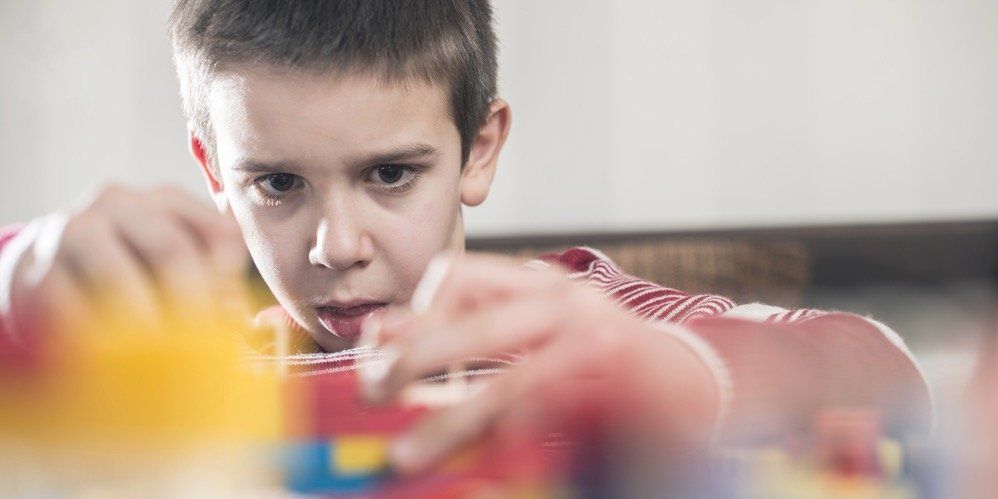
A child’s imagination is certainly something to behold. From pillow forts that double as outlying starbases, to walks in the forest that double as adventures travelling up and over the world’s tallest peaks, this gift that children possess- that of finding joy (not to mention awe and wonder) in the everyday is truly a thing of beauty. And, for a vast number of today’s children, one such imaginative outlet continues to be that of the lego brick; and why not?! These colourful shapes can turn the dullest of afternoons into an amateur engineer’s dream; vast worlds waiting to be created out of the simplest of shapes and forms.


On the other side of this creative coin (the adult side) sits the classic printer. From dot matrix, to inkjet, to laser, this technology has proved to be a complete game changer. The printer’s functions are incredibly useful, matched in practicality only by it’s complete and utter lack of “sleekness” and “sex appeal”. The printer is a boring machine. What it does is boring, its appearance (a gray box) is boring, and what it represents: endless cubicles, not unlike those in the cult classic film, Office Space, is boring; spitting out its’ “T.P.S reports”, until that fateful moment when the world is put on hold by some sort of “PC letter load” issue, or, worse yet, the dreaded paper jam.


But…


What if this incredibly useful (albeit, horribly yawn inducing) printer technology could somehow tap into the aforementioned imagination station that is the Lego brick? What if technological innovation could catch up to this childlike sense of awe and wonder? What if we could do things with the printer that would cause our young selves to flip with excitement; adult sized lego for the real world kinda stuff? Well, welcome to 2016.


3D Printing House

In a time when an ever increasing segment of society believes that proper housing should be a right and not a privilege, and in a world where variables such as human conflict and nature’s fury can wipe out established neighbourhoods in the blink of an eye, technology’s ability to speedily erect living spaces out of (literally) mounds of dirt is exciting, to say the least.


COST

Aside from the cost of building and transporting these large printers (which, at this point is substantial), the cost of building the home is limited: fewer labourers, fewer supplies to be shipped and stored, and the use of local, sustainable materials could lead to significant savings.


DESIGN INTRICACIES

Current construction/design engineering will soon be limited when compared to future computer based applications which are, as of this writing, being developed and tested. This is the power of technology at work. This is exciting.


CAVEAT

Now, it should be noted, at this point, that this field is still in its infancy. So there remains much to learn, and much to be done. Additionally, there are naysayers who remain firm in their position that, “this sort of fantasy will never become a reality”. To this we say, “it may be hard to be optimistic, to open up your imagination as you once did; but please try…just this once, for the rest of us.”


Printing houses. Seriously cool stuff.

SHARE THIS ARTICLE

RECENT POSTS

By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
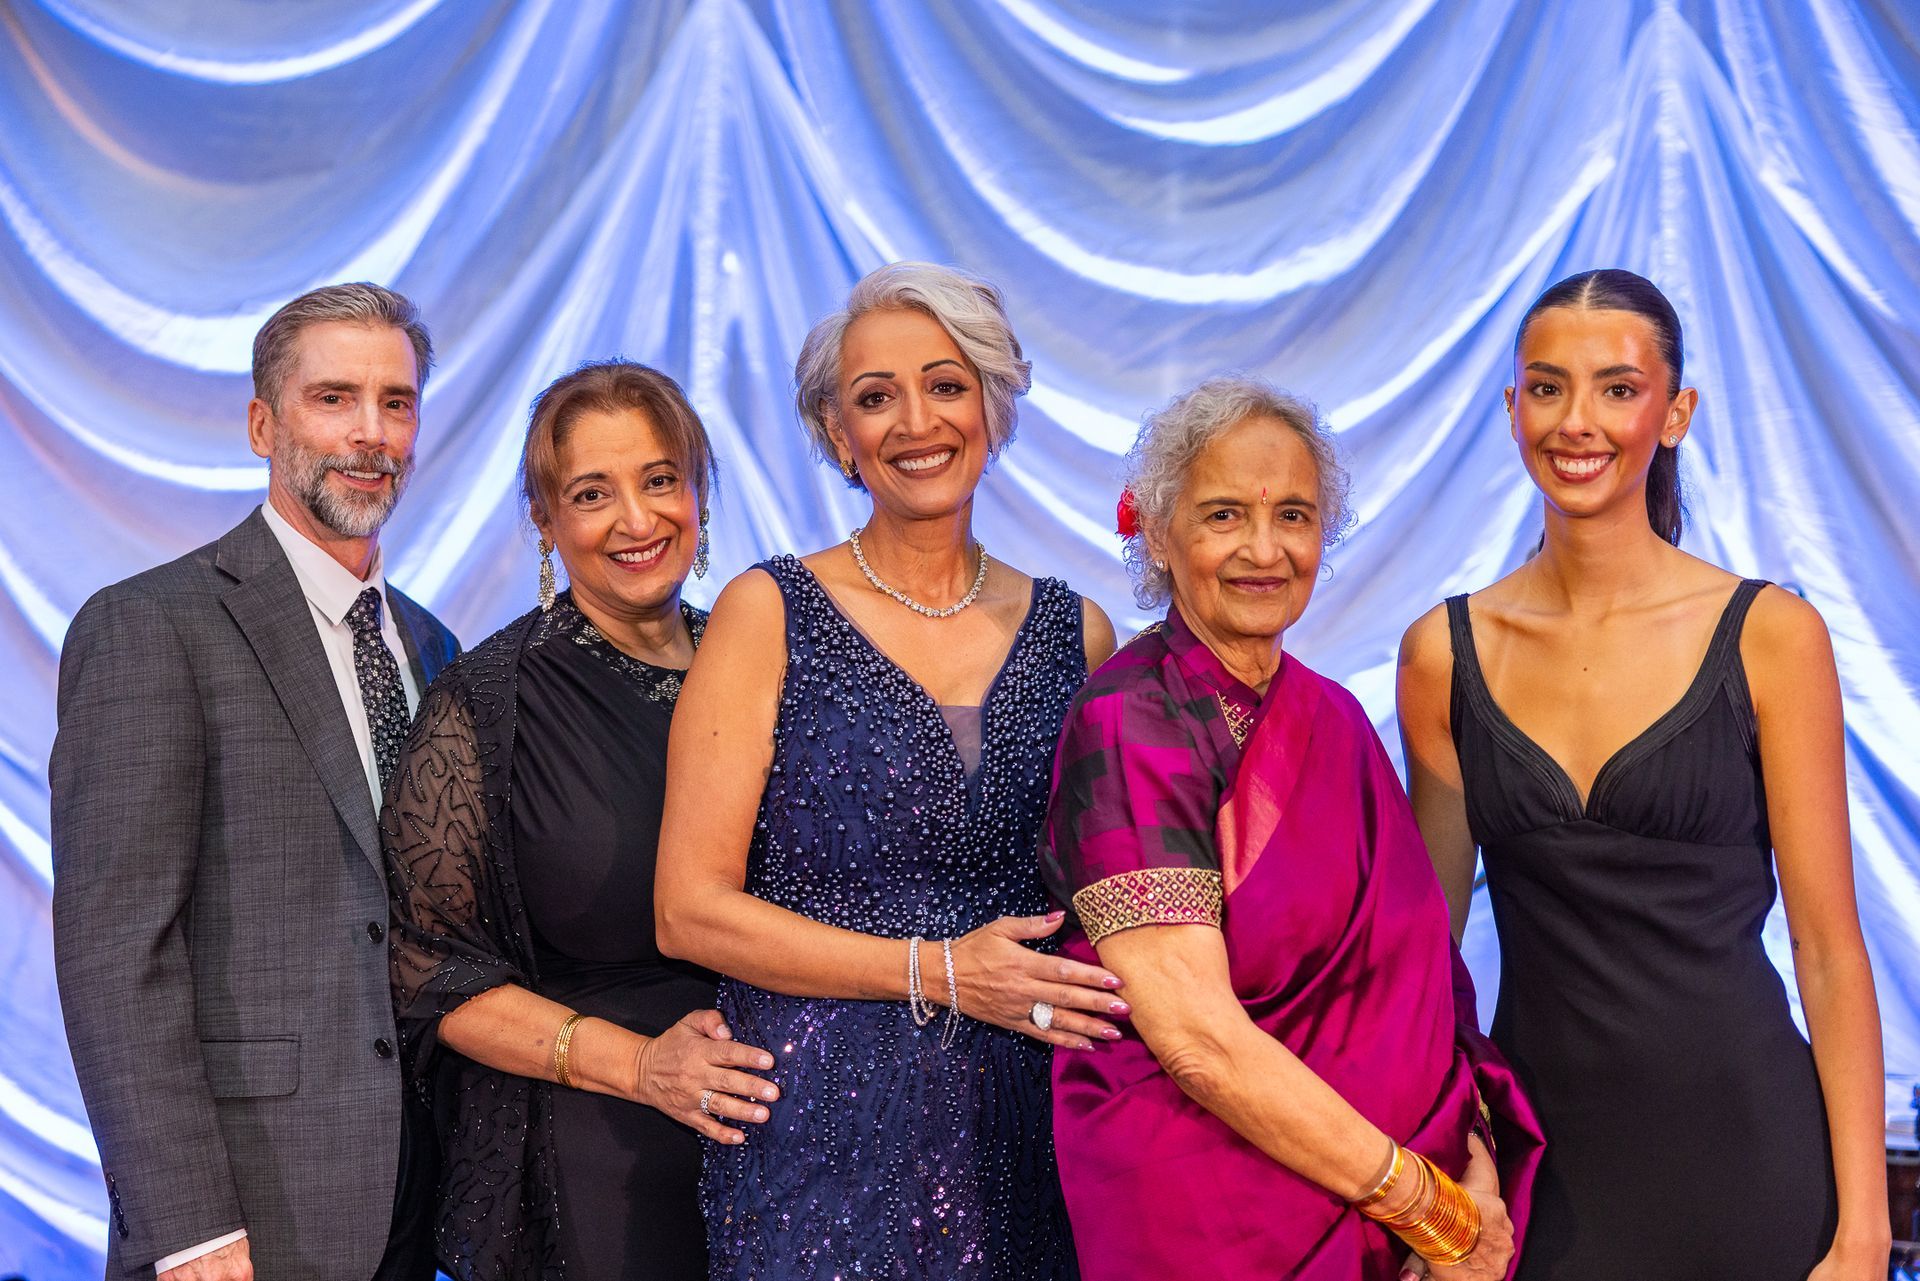
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.
By Sabeena Bubber • October 21, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.