Looking to Make a Big Impact on Your Savings This Year?
Sabeena Bubber • February 5, 2016

Here is a video published by Canadian finance expert Preet Banerjee that discusses the impact simply increasing your annual contributions by 5% per year can have to your savings.  https://youtu.be/Yq4Knh1d3V8


TRANSCRIPT

How small increases to your savings can make a big difference to your nest egg.


You’ve probably seen examples of how saving regularly can yield impressive results over time, for example if you saved $100 per month into a portfolio earning 5% per year starting at age 18 and until you turn 65, you would end up with around $225,000. But here’s a simple tip that can yield big results.


Increase your automatic contributions every new year!

Let’s see what happened to our 18 year old’s retirement portfolio if they only increase their annual contribution by 5% every January 1st. After saving $100 per month when they were 18, they would increase their savings by5% when they were 19, 5% of $100 is simply $5 so their new contribution increases to $105 per month. In year 3 when they turned 20 they increase this again by 5%. 5% of $105 is $5.25 adding this to $105 gives us a new monthly contribution a $110.25.


If they were able to continue with the annual contributions their nest egg at age 65 would increase from around $225,000 to just over $550,000. Now annual 5% increases are painless at the beginning but can become a bit more substantial after 40 years. The take-home message is that you may want to consider increasing your savings rate whenever you can buy as much as you can and the beginning of every new year is a great time to do just that your nest egg will thank you later.


SHARE THIS ARTICLE

RECENT POSTS

By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
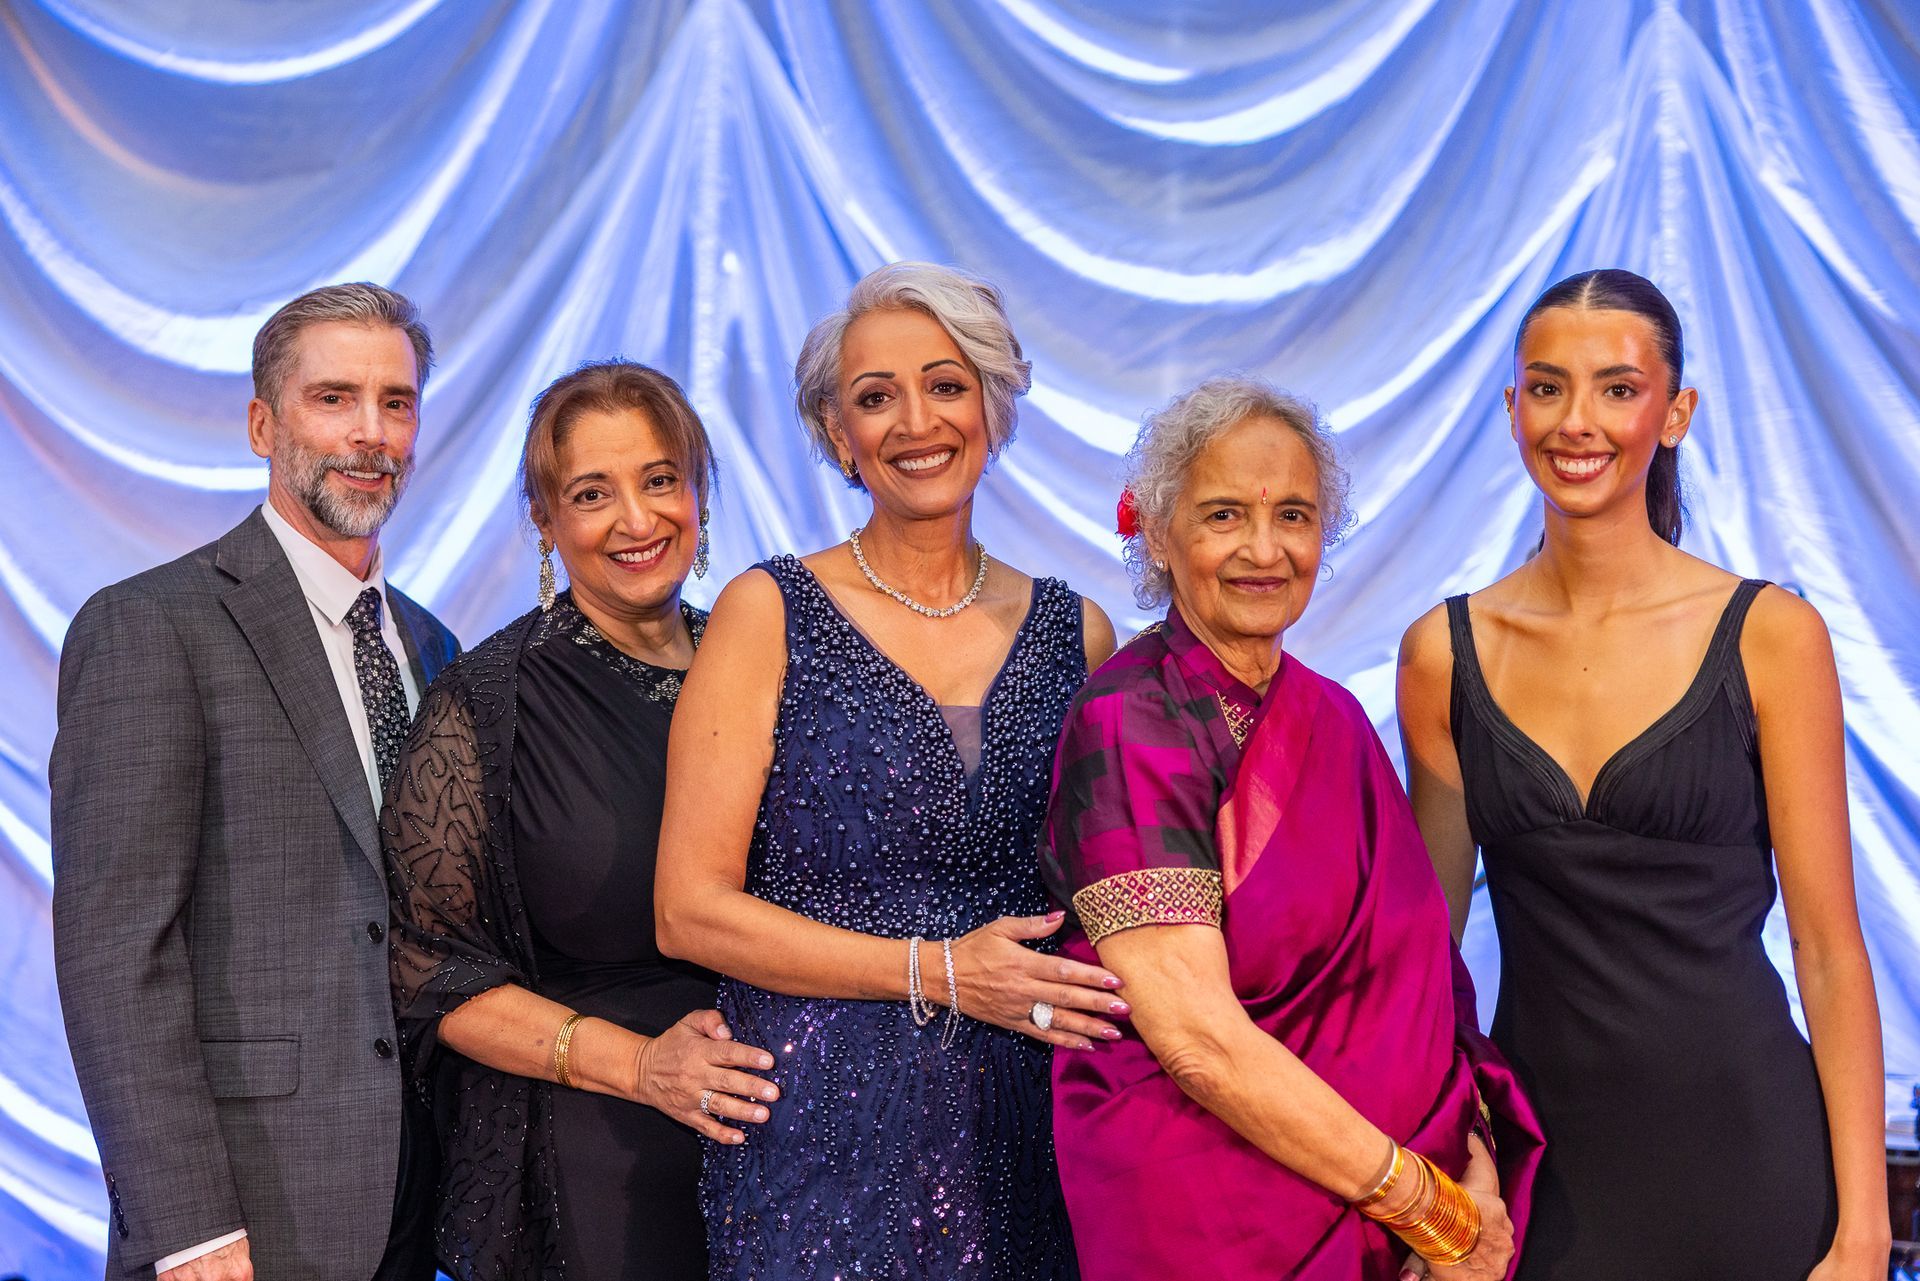
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.
By Sabeena Bubber • October 21, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.