Thinking of Selling? Call Me First!

Sabeena Bubber • July 17, 2018

If you've been thinking about selling your existing property, for whatever reason, it would be in your best interest to give me a call before you list for sale.

Here are a few scenarios that explain why...

Buying a New Property!

You have to live somewhere! If you plan on buying a new home using the equity from the sale of your existing home, you will most likely require a new mortgage. And just because you have qualified for a mortgage in the past doesn't guarantee you will qualify for a mortgage in the future. Making sure that your financing is in place before you go and list your house will make sure that you don't end up homeless!

This advice is good regardless if you are looking to purchase a home of lesser, the same, or greater value. We can also look at the options your existing mortgage has, you might actually be able to port your existing mortgage. Mortgage qualification is a tricky thing, it's best if you make your plans with an independent mortgage professional like me!

Not Buying a New Property.

Even if you aren't buying a new property, and you want to sell your existing property, it's still a good idea to contact me first as we can look at the cost of breaking your mortgage together. Unless you have an open mortgage, or a line of credit, there will be a penalty to break your mortgage. I can work with you on a plan to minimize your penalty, sometimes it's just a matter of waiting a few months. But you will never know unless you ask!

Marital Breakdown

Marriages break down, it's not ideal, but it happens. Oftentimes people who are going through a marital breakdown just want closure, and make decisions without really thinking them through. Instead of simply selling the family home, there are special programs that allow the home to be purchased by one of the parties involved as long as a legal separation agreement is in place.

So although you may think that the most logical person to call first when you're thinking of selling your home might be your Real Estate Agent, it's actually best if you have a financial plan already in place by the time you give them a call.

So if you're thinking of selling, please contact me anytime, I'd love to walk you through your options!

SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • November 4, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
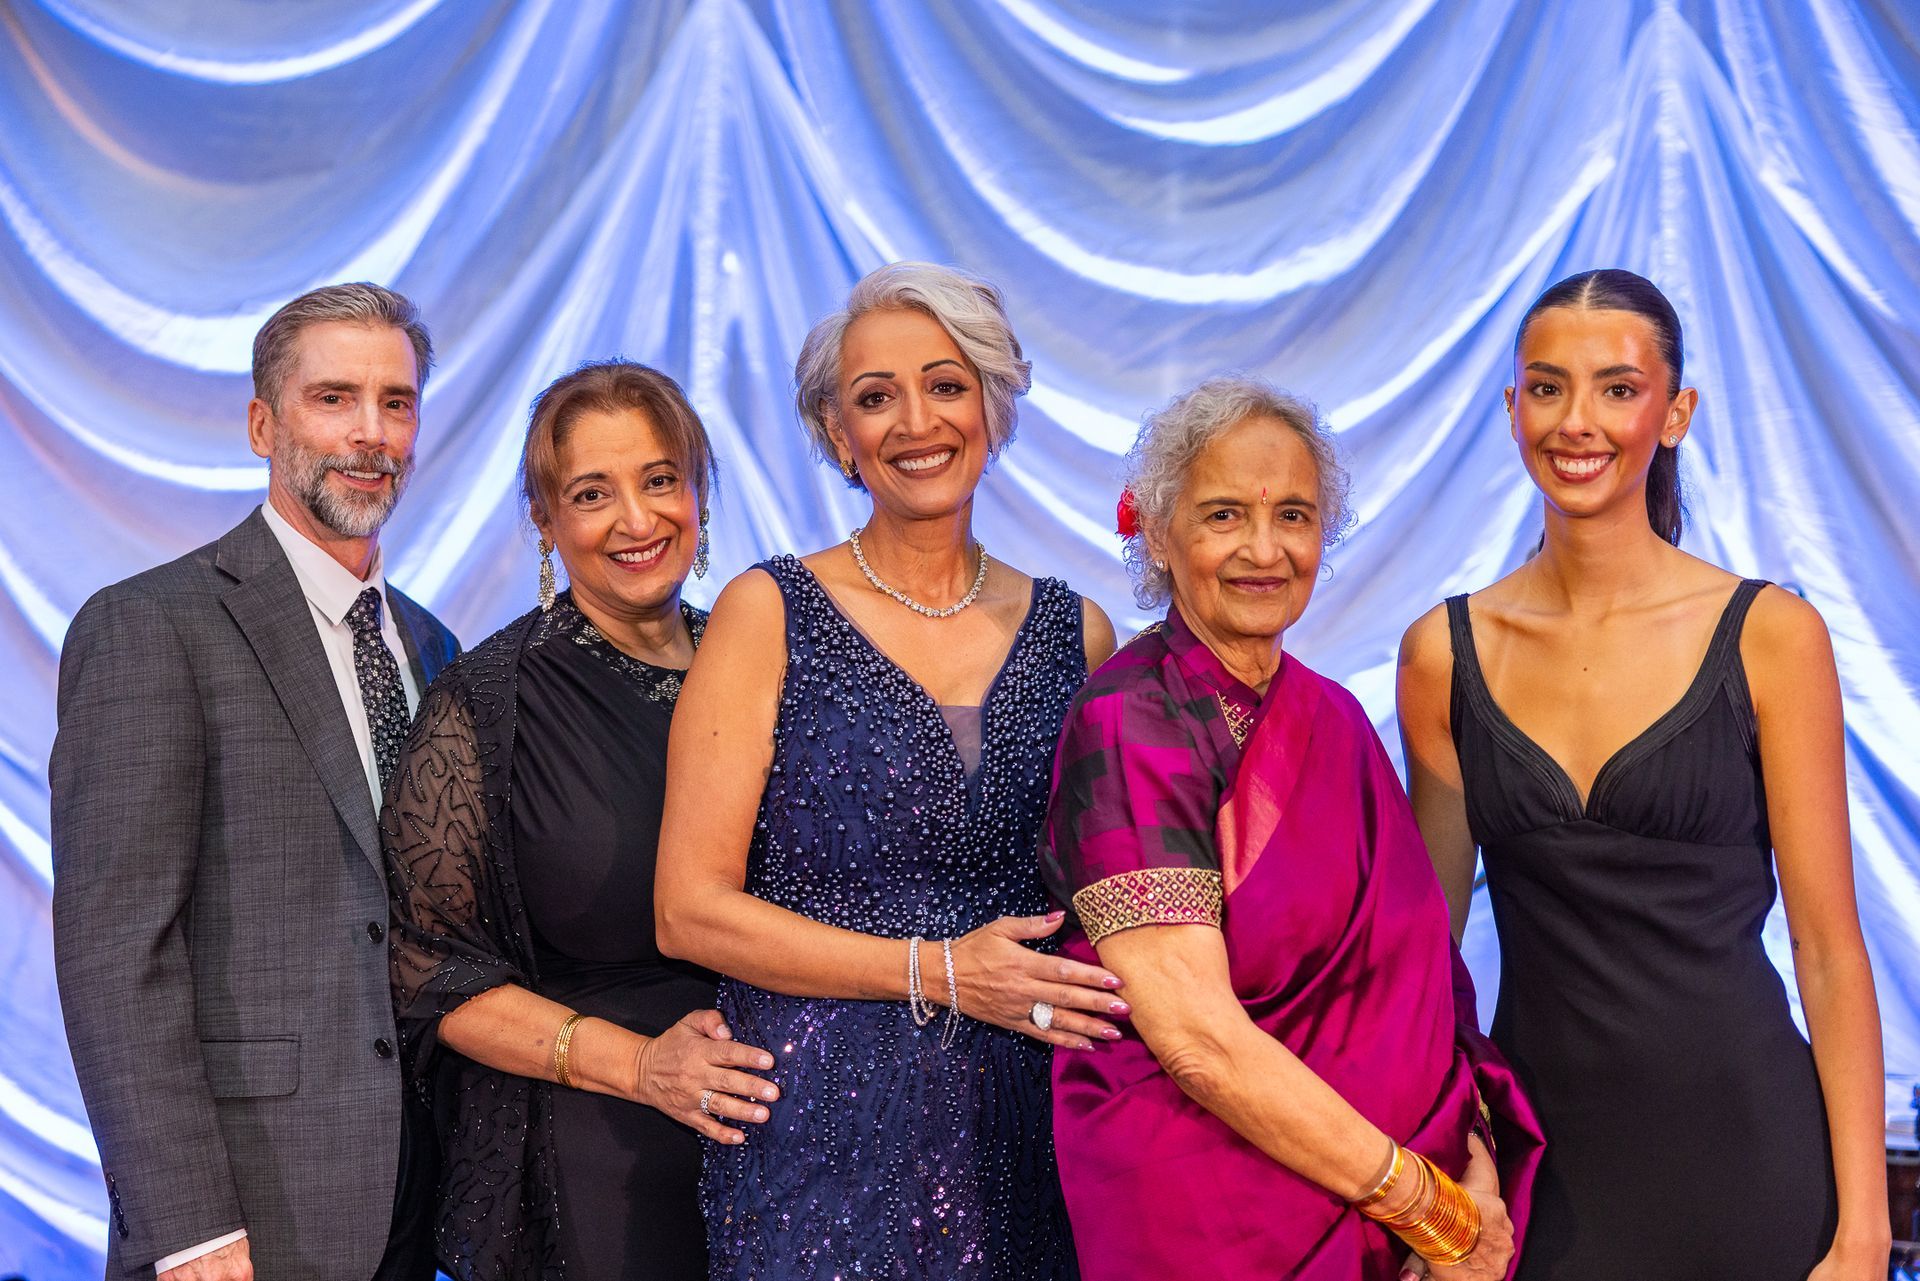
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.