Think Housing is Your Biggest Expense? Think Again!
Sabeena Bubber • September 20, 2017

Oftentimes people assume that housing is our single biggest expense, and although that was true in 1961, times have changed! According to research done by the Fraser Institute, last year the average Canadian family spent more on taxes than housing, food, and clothing combined. Here is the news release from the Fraser Institute along with a copy of the report. 

Now although I might not be able to help you reduce the amount of taxes you pay, if you would like to review your mortgage to see if you can save any money there, please don't hesitate to contact me anytime!  

NEWS RELEASE

Taxes—not housing and basic necessities—are largest Canadian household expense.

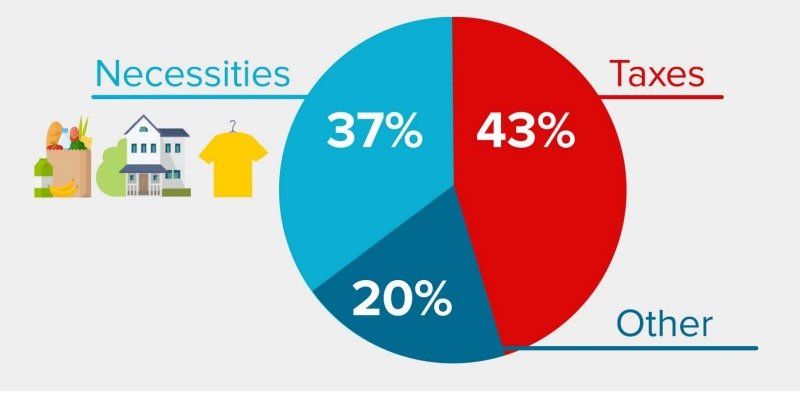
Despite high housing costs across the country, the average Canadian family spent more on taxes in 2016 than housing, food and clothing combined, finds a new study released today by the Fraser Institute, an independent, non-partisan Canadian public policy think-tank.

“Many Canadians may think housing is their biggest household expense, but in fact the average Canadian family spent more on taxes last year than on life’s basic necessities—including housing,” said Charles Lammam, director of fiscal studies at the Fraser Institute and co-author of the Canadian Consumer Tax Index, which tracked the total tax bill of the average Canadian family from 1961 to 2016.

Last year, the average Canadian family earned $83,105 and paid $35,283 in total taxes compared to $31,069 on housing (including rent and mortgage payments), food and clothing combined.

In fact, the average Canadian family paid nearly twice as much of their income in taxes (42.5 per cent) as they did for housing (22.1 per cent). The basic necessities of life, which include food, clothing and housing, amounted to just 37.4 per cent of income—still less than the percentage of income going to taxes.

This represents a marked shift since 1961, when the average Canadian family spent much less on taxes (33.5 per cent) than on food, clothing and housing (56.5 per cent).

The total tax bill reflects both visible and hidden taxes that families pay to the federal, provincial and local governments including income, payroll, sales, property, carbon, health, fuel and alcohol taxes and more.

Since 1961, the average Canadian family’s total tax bill has increased by a staggering 2,006 per cent, dwarfing increases in annual housing costs (1,527 per cent), clothing (677 per cent), and food (639 per cent).

Even after accounting for inflation, the tax bill has still increased 157.6 per cent over this period.

“Taxes help fund important public services that Canadians rely on, but the issue is the amount of taxes governments take compared to what Canadians get in return,” Lammam said.

“With more than 42 per cent of their income going to taxes, Canadians might ask whether they’re getting good value for their tax dollars.”

SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • November 4, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.