Be More Productive with the Rule of 3
Sabeena Bubber • January 26, 2016
This article was originally published on LinkedIn by Chris Bailey on Oct 28th 2015. Chris is a self-proclaimed Jedi Master at A Life of Productivity where he blogs about being productive.
FOR SOME STRANGE REASON, OUR BRAIN IS WIRED TO THINK IN THREES.
HERE’S THE RULE OF 3:
- At the start of every morning, fast-forward to the end of the day and ask: When the day is done, what three things will I want to have accomplished?
- Do the same at the start of every week.
- It fits with the way we think. For some reason that I haven’t been able to figure out, from childhood our brain is wired to think in threes.
- It’s hard to keep in mind what’s important. While you won’t remember a whole laundry list of things to do when you’re in the trenches, you’ll remember your three intentions.
- You decide what you don’t By picking the three main things you want to accomplish that day, you have taken the time to separate what’s important from what isn’t.
- It only takes a minute. For every minute you spend using the Rule of 3, you gain back at least 10 minutes of productivity.
- It helps you work more deliberately. Productivity is the process of working more deliberately, with intention. The Rule of 3 helps you to step back, determine what’s important, and then reflect throughout the day on whether you’re spending your time on the right things. The intention behind your actions is like the shaft behind an arrowhead. I haven’t found a better rule for setting intentions every day.
- The rule lets you consider your limits. Each day you only have so much time, attention, and energy. Productivity is a process of understanding your constraints. The Rule of 3 helps you think about how much want to accomplish, and then, over time adjust to how much you actually can accomplish once you better understand your limits. At first, I overestimated how much I could get done when defining my three things; later I underestimated what I was capable of. Finally I settled into an equilibrium where I understood how much I could do every day. That awareness has become, as Steve Jobs might say, insanely valuable.
I’ve found the exact same thing.
SHARE THIS ARTICLE
RECENT POSTS
Your Lender Is Not Obligated to Renew Your Mortgage Many homeowners assume that if they’ve made every mortgage payment on time, their lender is automatically required to renew their mortgage at the end of the term. That’s a common belief—but it isn’t true. When you sign a mortgage, you’re agreeing to a contract for a specific term . Once that term ends, the lender has the legal right to either renew the mortgage or call the loan . There is no obligation to offer a renewal. In practice, most lenders do renew mortgages—but certain situations can prevent that from happening. Reasons a Lender May Decline to Renew A lender may choose not to renew if: Mortgage payments were missed during the term A bankruptcy or consumer proposal has occurred There is a separation or divorce Employment or income has changed A borrower on the mortgage has passed away The lender no longer prefers the property’s location or market The lender is no longer licensed to lend in Canada Even one of these factors can change how a lender views the risk. Why This Matters Because renewal is not guaranteed, waiting until the last minute can put you in a difficult position. Understanding this reality early gives you time and control. How to Protect Yourself at Renewal The best approach is to be proactive. Ideally, you should begin reviewing your options 120 days before your mortgage term ends . This gives you enough time to explore alternatives and make informed decisions—rather than reacting under pressure. Even if your current lender offers a renewal, that’s just one option , not automatically the best one. The lender that was right for you years ago may no longer offer the most competitive rate, terms, or flexibility today. The goal at renewal isn’t convenience—it’s reducing your total cost of borrowing and choosing terms that align with your current situation. Why Work With an Independent Mortgage Professional Working with an independent mortgage professional ensures someone is advocating for you , not the lender. Instead of being limited to one set of products, you can compare options across multiple lenders and choose the solution that best protects your interests. Final Thoughts Whether your lender is offering a renewal or not, the smartest move is to review all your options before signing anything. If your mortgage is coming up for renewal—or if you want to plan ahead—feel free to connect anytime. I’d be happy to help you protect your options and make a confident decision.
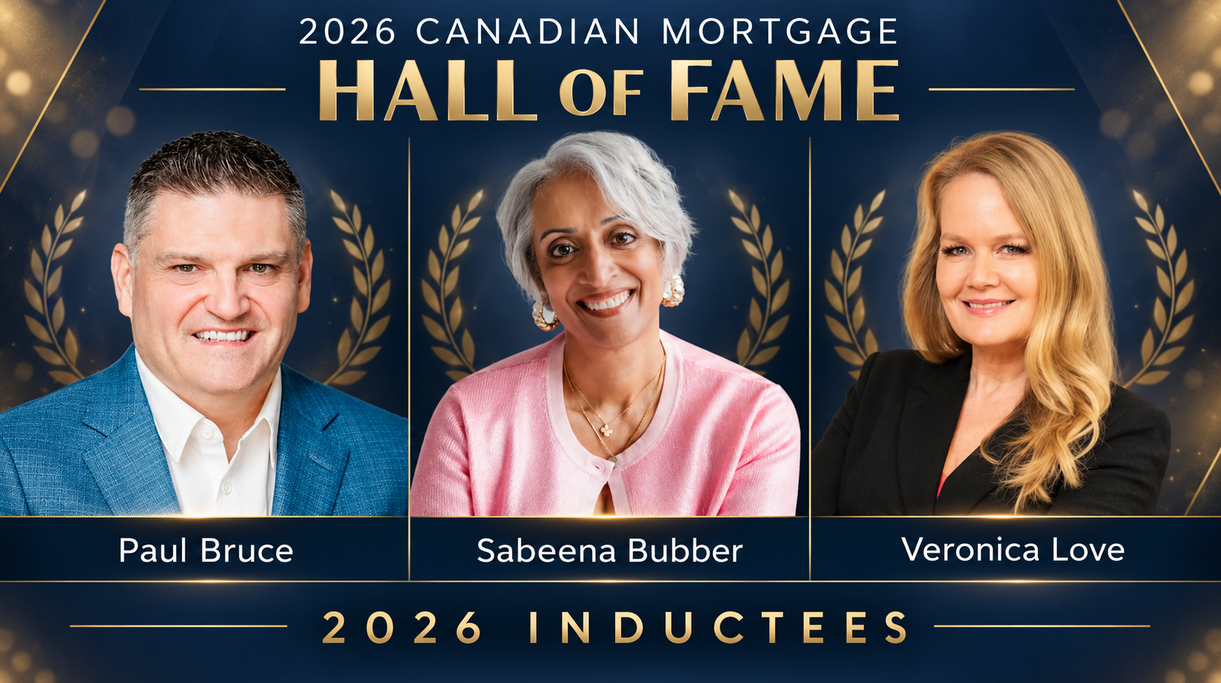
Sabeena Bubber is a 2026 Canadian Mortgage Hall of Fame inductee, recognized for mortgage industry leadership, client service, and community impact.
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.