The Budgeting Resource Everyone Has (And Nobody Uses)
Sabeena Bubber • January 12, 2016

Does This Sound Familiar?


You’ve read a book or a blog series or watched a show about budgeting and getting your money under control. You’re all fired up, ready to really get it together, and get to work on that budget. The first few lines are easy:


Monthly net income? Read it off the paycheque, check.


Mortgage payment? Burned in the memory, check. Oh, man. This budgeting stuff is easy.


Groceries? Uh…well, we usually shop once a week (unless we forgot something) and it usually comes in between $120-$180…I’ll put $150.


Clothing? Oh, man. I don’t know, $50? Except in September, when the kids go back to school, and October when their feet maliciously grow and we have to buy new running shoes with only one month until the snow falls…and April, when we realize it’s too warm for winter coats and too cold for sweaters…


Entertainment? Erm…let’s say $10. I dunno, do late charges at the library count?


When the time comes to “stick to the budget” and that budget is just a series of made up numbers, what happens?


Or This?

You take the advice most people are offering about controlling your spending: you begin to track your income. You get a notebook and a pen, and you write down every penny you spend, every day. Until Thursday comes along, and you’re so busy that you just keep the receipts in the book, because you know you’ll have time on Friday and you’ll remember, but Friday becomes Saturday two weeks later, and you’re sitting in front of a pile of little pieces of paper, trying to forensically reconstruct seventeen days of spending and hoping that missing the two pocketfuls of receipts that went through the wash won’t screw you up too much.


Maybe, instead of the notebook or spreadsheet, you signed up for Mint or Quicken or YNAB instead, and you faithfully input or categorize all of your spending for almost a month. And then suddenly your checking account (according to the program) has $1,315.92 in it, when your checking account (according to reality) has $541.01. And you can’t find the mistake.


When your books are a mess and you actually have no idea how closely you’ve been “sticking to the budget”, what happens?


Protip: Use What You Already Have to Start Budgeting Well


Look, these things happen, even to someone who ::cough:: has been tracking her transactions and living on a spending plan for ::coughtenyearscough:: But when one of these is your first experience with the whole budgeting thing, it can very, very easily be your last. Or your last for a while.


I truly don’t understand why the inevitable advice for first-timers is always A) write out a budget and/or B) track your spending. The only people who won’t get lost in the land of 78 spending categories and account reconciliation are the ones who probably wouldn’t have needed to read the book or watch the TV show to get themselves organized, and were going to be fine anyway.


The frustration goes away with time and practice, it really does. Any budgeting system will work if you give yourself enough time to learn and adapt to it, honestly. But why go through all the aggravation of trying to live by a guess-timated budget if you don’t have to?


Download Transactions

If you’re convinced that some part of budgeting is worth doing, then the first place to start isn’t how you’re going to spend in the future; it’s how you’ve already spent in the past.


You have years worth of data lying dormant in your bank and credit card history as we speak – a complete picture of how you spent your money when you weren’t paying attention, and accessing it is as simple as downloading a good sample size to a spreadsheet, sorting them out, and adding them up.


Easy For Me To Say

This is one of those pieces of advice that could very easily become that “just” advice that I hate so much.

I use spreadsheets every day (and love every minute of it) so this is an easy thing for me to do and recommend. If you don’t speak spreadsheet very fluently, this exercise might be as frustrating as trying to guess how much you’re going to spend on clothes in the next _insert arbitrary period of time here_.


But, like most things prefaced with “just”, it might be worth your time and effort to try. If you have even a passing familiarity with rows, columns, and cells, and know how to use the “sort” function, examining your past spending in aggregate is a good way to set yourself up for success with your future spending.


Why start with a guess when you can start with data?


Note: Some readers have mistakenly read this as a recommendation to use spreadsheets to track ongoing spending, to which I can only say: please don't use spreadsheets to track your spending unless you're a confirmed spreadsheet ninja. /PSA

SHARE THIS ARTICLE

RECENT POSTS

By Sabeena Bubber • October 21, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.
By Sabeena Bubber • October 14, 2026
Your Lender Is Not Obligated to Renew Your Mortgage Many homeowners assume that if they’ve made every mortgage payment on time, their lender is automatically required to renew their mortgage at the end of the term. That’s a common belief—but it isn’t true. When you sign a mortgage, you’re agreeing to a contract for a specific term . Once that term ends, the lender has the legal right to either renew the mortgage or call the loan . There is no obligation to offer a renewal. In practice, most lenders do renew mortgages—but certain situations can prevent that from happening. Reasons a Lender May Decline to Renew A lender may choose not to renew if: Mortgage payments were missed during the term A bankruptcy or consumer proposal has occurred There is a separation or divorce Employment or income has changed A borrower on the mortgage has passed away The lender no longer prefers the property’s location or market The lender is no longer licensed to lend in Canada Even one of these factors can change how a lender views the risk. Why This Matters Because renewal is not guaranteed, waiting until the last minute can put you in a difficult position. Understanding this reality early gives you time and control. How to Protect Yourself at Renewal The best approach is to be proactive. Ideally, you should begin reviewing your options 120 days before your mortgage term ends . This gives you enough time to explore alternatives and make informed decisions—rather than reacting under pressure. Even if your current lender offers a renewal, that’s just one option , not automatically the best one. The lender that was right for you years ago may no longer offer the most competitive rate, terms, or flexibility today. The goal at renewal isn’t convenience—it’s reducing your total cost of borrowing and choosing terms that align with your current situation. Why Work With an Independent Mortgage Professional Working with an independent mortgage professional ensures someone is advocating for you , not the lender. Instead of being limited to one set of products, you can compare options across multiple lenders and choose the solution that best protects your interests. Final Thoughts Whether your lender is offering a renewal or not, the smartest move is to review all your options before signing anything. If your mortgage is coming up for renewal—or if you want to plan ahead—feel free to connect anytime. I’d be happy to help you protect your options and make a confident decision.
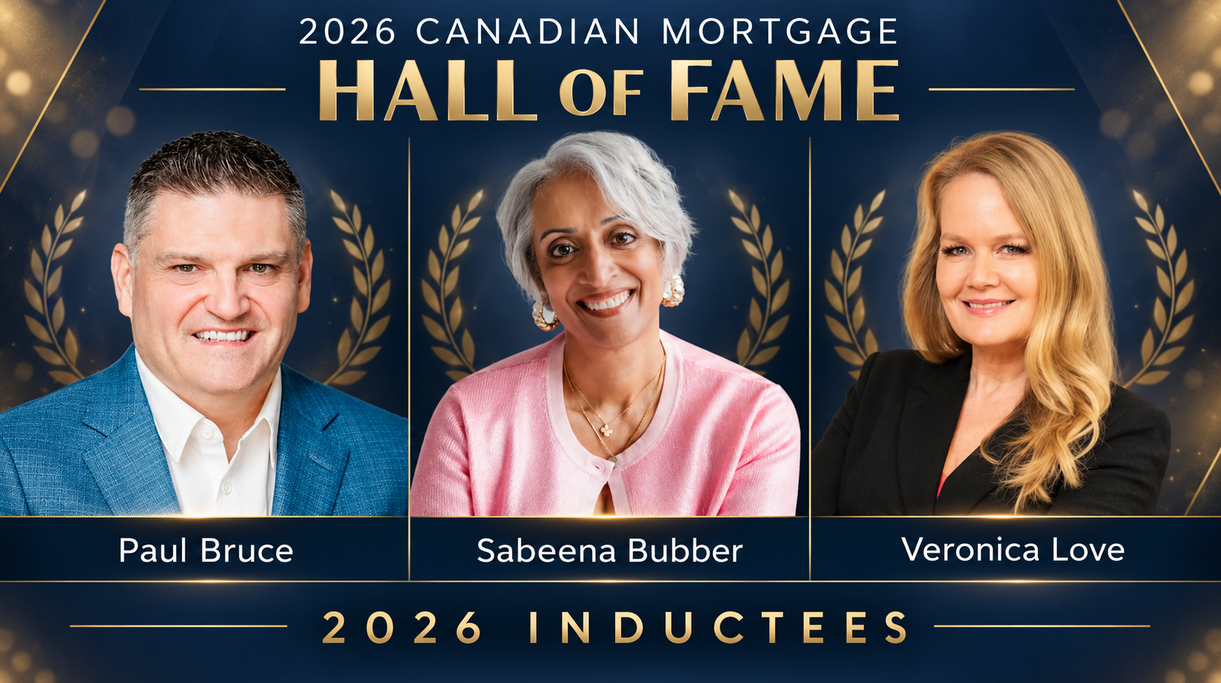
Sabeena Bubber is a 2026 Canadian Mortgage Hall of Fame Inductee
By Sabeena Bubber • October 13, 2026
Sabeena Bubber is a 2026 Canadian Mortgage Hall of Fame inductee, recognized for mortgage industry leadership, client service, and community impact.