Introducing the Tesla Powerwall

Sabeena Bubber • June 16, 2015

A BATTERY DESIGNED TO POWER YOUR HOME


If you haven’t heard of the Tesla Powerwall yet, but your initial thoughts are that it sounds like something out of a comic book, you might not be that far off. Tesla’s founder Elon Musk might actually be a real life Avenger (you know… the superhero kind)… but we will get to that later.


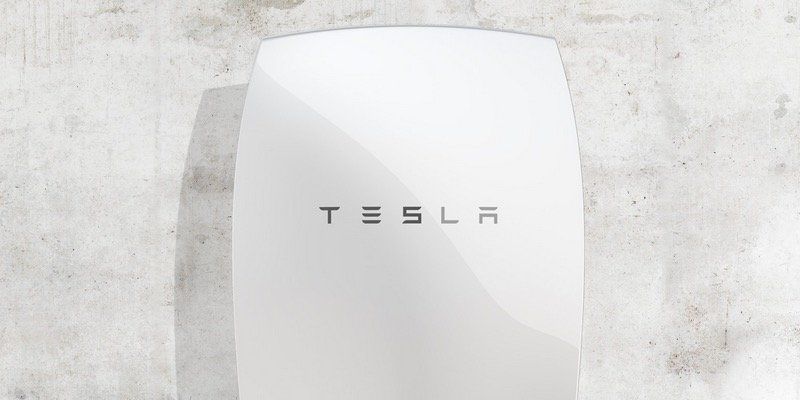
Tesla Motors, a company known for making electric cars has recently taken a huge step forward in the renewable energy world and has opened a division called Tesla Energy. Tesla Energy has announced the release of it’s first product, the Tesla Powerwall which uses the technology present in the batteries of Tesla cars and has given it an application to power houses and buildings.


The 7kWh unit will sell for $3,000, while the 10kWh unit will go for $3,500, with the goal of shipments starting summer 2015! (However according to one news story, they are already sold out until 2016, I guess there is real demand).


Here is some of the official jargon from the Tesla Energy Press release:


“The Powerwall is a rechargeable lithium-ion battery designed to store energy at a residential level for load shifting, backup power and self-consumption of solar power generation. Powerwall consists of Tesla’s lithium-ion battery pack, liquid thermal control system and software that receives dispatch commands from a solar inverter. The unit mounts seamlessly on a wall and is integrated with the local grid to harness excess power and give customers the flexibility to draw energy from their own reserve.”


Harness-Store-Power-1

Basically this is a battery for your house that stores power from the grid or solar panels. This is a huge step towards making "getting off the grid" accessible to the average homeowner.

Here is a list of resources that explain the Powerwall in greater detail than I can including a video of the launch and some recent press.

Tesla Powerwall As for Tesla founder Elon Musk, here is a fun infographic that compares him to Tony Stark or Ironman from the Marvel Comics.

Courtesy of: VCARS

SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • November 4, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.