"I Would Recommend Sabeena Without Hesitation"
Sabeena Bubber • December 18, 2014

FROM A RECENT CUSTOMER SURVEY

As a way to make sure I am always paying attention to the service I provide my clients, I use a survey after a mortgage funds. It’s a simple question and answer format and provides me with tremendous insight.


I wanted to share one of my most recent testimonials (with his permission of course) with you as it highlights that the mortgage process isn’t always straight forward. Often times lenders products aren’t always what we want them to be (or need them to be)… and in this case, it meant changing lenders completely to get the right product.


I believe this is one of the biggest benefits of working with me as your mortgage professional, I work for you and not the lenders. It sounds so cliche, but it’s the truth. My goal is to make sure you find the right product, regardless of how many lenders that means working with.


From Glen April of 2014,

Would you recommend your Broker to a friend or Relative?

YES. Without Hesitation.


What aspect of our service did you value the most?

We appreciated Sabeena’s professional and creative approach to our financing needs despite our somewhat unconventional banking history of 3 countries in 5 years and was able to provide timely solutions as well as several options for both the builder’s loan and finally our mortgage.


Do you have any suggestions on how we could improve our service to you and to other clients in the future?


The only surprise along the way was with the initial builder’s loan provider. Their initial offering letter made it seem as if we would receive the loan proceeds in 2 sums; initial advance to proceed and at 80% completion we would receive the balance to get the house to completion. The actual loan contract had different language and while there were some tense moments Sabeena was able to quickly provide a second mortgage option. I still feel that was a slight of hand trick by the first lender.


Will you recommend us to your friends/family/colleagues? and if so, what would you tell them about us?


As stated above I would recommend Sabeena -and have done so already- without hesitation and when I have been asked about Sabeena I have described her professionalism and that she genuinely cares about her clients and takes an interest in their needs that is far too often lacking from loan departments in major banks. If you don’t fit their mould they don’t seem to care too much about your needs. Sabeena understands and appreciates that flexibility and creatively addressing financing needs can be a very good business on both sides of the relationship.


SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • November 4, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
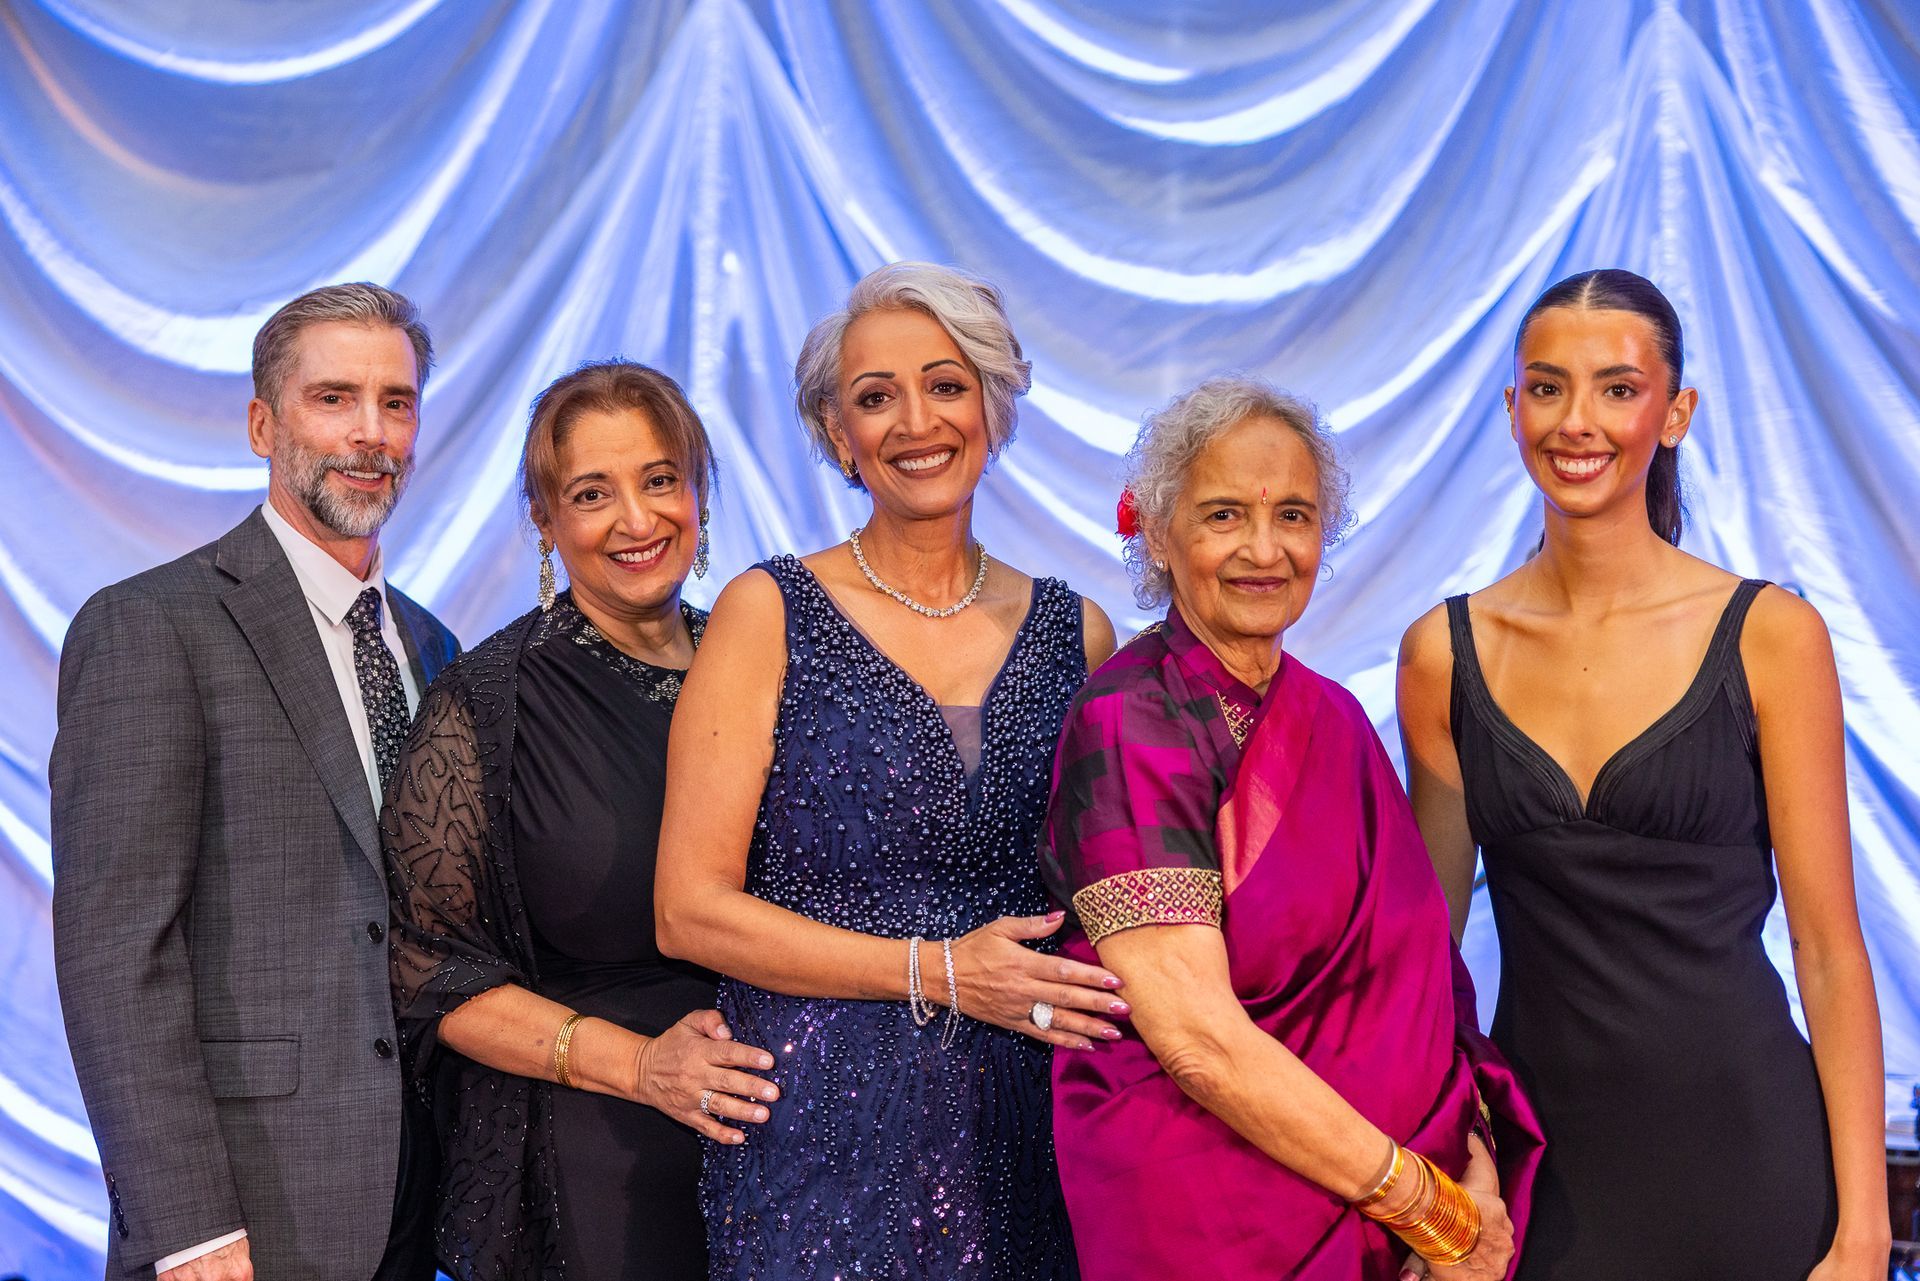
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.