14 THINGS I BET YOU DON’T KNOW ABOUT CELIAC DISEASE
Sabeena Bubber • June 19, 2015

As I have been swamped with work lately, and I have shared quite a few of my favourite recipes on my blog, I have decided to share some more information about Gluten Free cooking and Celieac Disease on my blog from other sources than just my own kitchen. Also I will (for the summer anyway) be moving to a post every other week rather than every week!


Have a happy productive summer, that is my plan anyway! With that said…


Here is a list of 14 things you need to know about celiac disease. Because celiac disease is NOT a fad!

1. Celiac Disease is an Autoimmune Disease

2. There Are Over 300 Known Symptoms of Celiac Disease

3. Digestive Symptoms Are NOT the Only Symptoms of Celiac Disease

4. More People Have Celiac Disease Than Crohns, Colitis, and Cystic Fibrosis Combined

5. Celiac Disease is Hereditary

6. Left Untreated, Celiac Disease Can Lead to Additional Serious Health Problems

7. Many People with Celiac Disease Report Having “Brain Fog”

8. 83% of Americans with Celiac Disease Are Still Suffering Without a Diagnosis

9. The Later the Age of Diagnosis, the Greater the Chance of Developing Another Autoimmune Disorder

10. It is Estimated That Up to 20% of People Diagnosed With Celiac Disease Have Persistent Symptoms While on a Gluten-Free Diet

11. Consuming the Smallest Amount of Gluten Can Make a Person With Celiac Disease Very Ill

12. Commonly, People With Celiac Disease Experience Several Nutritional Deficiencies

13. 15-25% of People With Celiac Disease Are Also Affected by Dermatitis Herpetiformis

14. Celiac Disease Foundation Drives Diagnosis and Treatment of Celiac Disease Through Advocacy, Education, and Advancing Research to Improve the Quality of Life for All People Affected by Gluten-Related Disorders


Via celiac.org

Celiac Disease Foundation (CDF) is a 501 (c )(3) non-profit organization established in 1990. With vital programs and services for the public, patients, healthcare professionals, and the food industries, CDF meets the growing public health challenge of diagnosing and treating celiac disease and other gluten-related disorders.

This list was originally published on BuzzFeed here.


SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • October 14, 2026
Your Lender Is Not Obligated to Renew Your Mortgage Many homeowners assume that if they’ve made every mortgage payment on time, their lender is automatically required to renew their mortgage at the end of the term. That’s a common belief—but it isn’t true. When you sign a mortgage, you’re agreeing to a contract for a specific term . Once that term ends, the lender has the legal right to either renew the mortgage or call the loan . There is no obligation to offer a renewal. In practice, most lenders do renew mortgages—but certain situations can prevent that from happening. Reasons a Lender May Decline to Renew A lender may choose not to renew if: Mortgage payments were missed during the term A bankruptcy or consumer proposal has occurred There is a separation or divorce Employment or income has changed A borrower on the mortgage has passed away The lender no longer prefers the property’s location or market The lender is no longer licensed to lend in Canada Even one of these factors can change how a lender views the risk. Why This Matters Because renewal is not guaranteed, waiting until the last minute can put you in a difficult position. Understanding this reality early gives you time and control. How to Protect Yourself at Renewal The best approach is to be proactive. Ideally, you should begin reviewing your options 120 days before your mortgage term ends . This gives you enough time to explore alternatives and make informed decisions—rather than reacting under pressure. Even if your current lender offers a renewal, that’s just one option , not automatically the best one. The lender that was right for you years ago may no longer offer the most competitive rate, terms, or flexibility today. The goal at renewal isn’t convenience—it’s reducing your total cost of borrowing and choosing terms that align with your current situation. Why Work With an Independent Mortgage Professional Working with an independent mortgage professional ensures someone is advocating for you , not the lender. Instead of being limited to one set of products, you can compare options across multiple lenders and choose the solution that best protects your interests. Final Thoughts Whether your lender is offering a renewal or not, the smartest move is to review all your options before signing anything. If your mortgage is coming up for renewal—or if you want to plan ahead—feel free to connect anytime. I’d be happy to help you protect your options and make a confident decision.
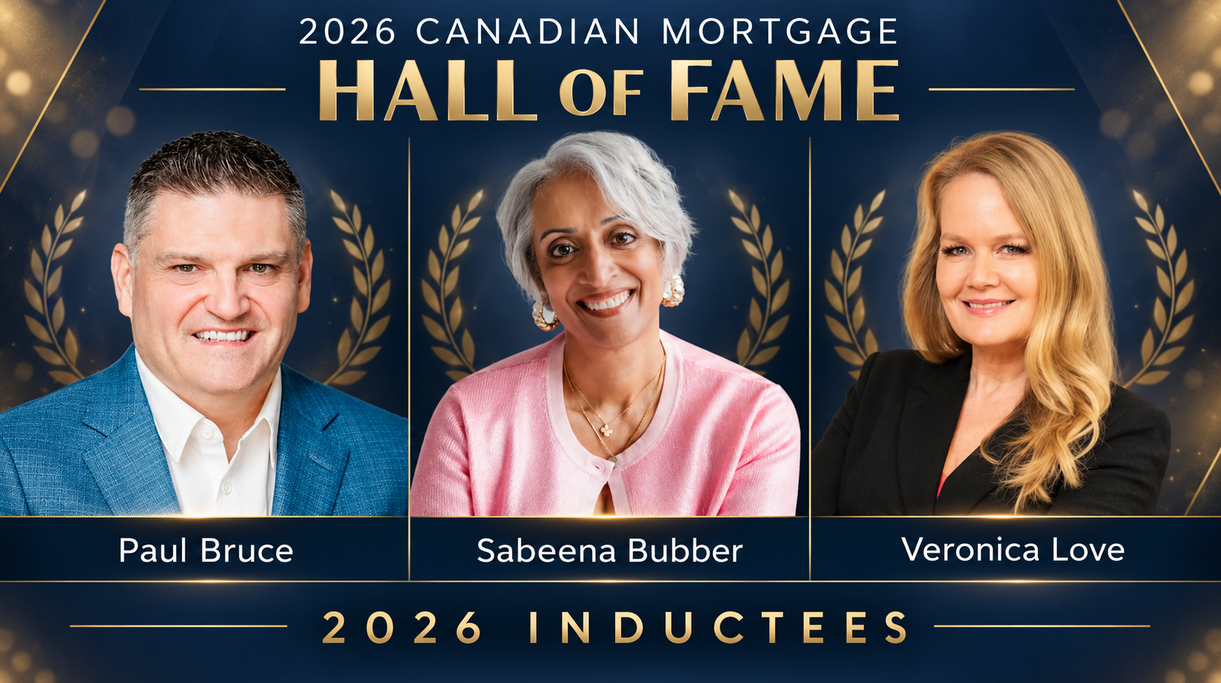
Sabeena Bubber is a 2026 Canadian Mortgage Hall of Fame Inductee
By Sabeena Bubber • October 13, 2026
Sabeena Bubber is a 2026 Canadian Mortgage Hall of Fame inductee, recognized for mortgage industry leadership, client service, and community impact.
By Sabeena Bubber • October 7, 2026
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.